Unlocking Economic Potential: The Interplay of News, Education, Benefits, and Finance
Anúncios
Ever feel like you’re playing a financial game where the rules keep changing? One day, a news report impacts your investments; the next, a new skill is suddenly in high demand. It’s easy to feel like you’re always one step behind, reacting to economic shifts rather than anticipating them. This feeling of uncertainty isn’t just in your head; it’s the result of powerful, interconnected forces at play.
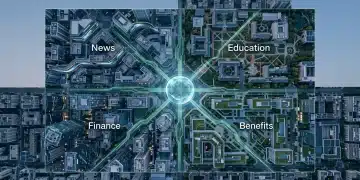
The modern economy is driven by four critical pillars: the news that shapes market sentiment, the education that builds valuable skills, the employment benefits that create a safety net, and the financial strategies that tie it all together. These are not separate subjects to be managed in isolation. Instead, they form a dynamic system where a change in one area creates ripple effects across all the others. Understanding this interplay is the difference between simply earning a living and actively building wealth.
This article demystifies that complex relationship. We will explore the foundational link between information and economic behavior, demonstrating how education acts as a direct catalyst for financial mobility. we’ll break down how to optimize often-overlooked benefits and integrate them into a cohesive financial plan. By connecting these dots, you can move from a reactive to a proactive stance, positioning yourself to navigate and capitalize on emerging economic trends.
The Foundational Link: How Information Shapes Economic Behavior
Making financial choices without reliable information is like trying to navigate a new city without a map. You might get lucky, but the odds are stacked against you. Access to timely and accurate news—from inflation reports to shifts in government policy—directly shapes our economic decision-making. This information isn’t just background noise; it provides the context for every dollar you earn, save, or invest.
Anúncios
The market’s reaction to new information can be swift and significant. A study from the National Bureau of Economic Research found that unexpected monetary policy announcements can cause stock market volatility to jump by over 70% within the first hour. It’s an immediate financial ripple effect. This underscores how critical it is to understand the data-driven analysis of our interconnected world.
But what does a central bank announcement really mean for your personal finances? Surprisingly, the connection is quite direct. Interest rate hikes can influence your mortgage payments, while trade policy updates might affect the price of your groceries (thanks to supply chain adjustments). Avoiding common pitfalls in the information maze is necessary for protecting your financial well-being.
Anúncios
Ultimately, a steady flow of quality information allows individuals and businesses to move from a reactive to a proactive stance. Understanding these foundational links is the first step toward building a more secure financial future.
Education as an Economic Catalyst: Investing in Human Capital
While timely news provides the map, education provides the engine for economic mobility. Investing in human capital development is not just about personal enrichment; it’s a direct investment in national productivity and financial resilience. When a workforce gains new skills, it can produce higher-value goods and services, which in turn boosts the entire economy. It is a powerful chain reaction.
This isn’t just theory. The data suggests a clear correlation between educational attainment and economic output. Countries that prioritize accessible and quality education consistently see higher GDP per capita. Think of education as infrastructure for the mind—just as roads and bridges facilitate commerce, schools and training programs facilitate innovation and efficiency. What many people miss, is how to strategically approach this investment on a personal level, a challenge explored in our beginner’s guide to financial planning.
Return on Investment: Educational Pathways and Earning Potential
Choosing an educational path is one of the most significant financial decisions a person will ever make. The debate often centers on traditional university degrees versus vocational training, but the numbers reveal a more complex picture. The return on investment (ROI) varies dramatically based on the field of study, cost of tuition, and the time spent out of the workforce. For many, the idea is to minimize debt while maximizing future income, but is that always the reality?
A detailed breakdown shows that different paths can lead to financial success. The key is aligning the educational investment with in-demand skills. A report from the Georgetown University Center on Education and the Workforce provides a useful framework for comparing these outcomes.
| Educational Path | Avg. Cost | Median Lifetime Earnings |
|---|---|---|
| Vocational Certificate (e.g., HVAC Technician) | $16,000 | $2.2 Million |
| Associate’s Degree (e.g., Dental Hygienist) | $38,000 | $2.6 Million |
| Bachelor’s Degree (e.g., Software Engineer) | $127,000 | $3.5 Million |
The table clearly shows higher lifetime earnings potential with a bachelor’s degree, but it comes at a significantly higher upfront cost and time commitment. The underrated factor here is the skill gap finance—the cost of not working while studying. A vocational path allows an individual to enter the workforce and start earning almost two years sooner than someone pursuing a four-year degree. Understanding these trade-offs is critical to avoiding some of the common financial pitfalls young professionals face.
Ultimately, the challenge is not just about getting a degree but about acquiring relevant skills that the market demands. The growing gap between university curricula and employer needs means that continuous learning and upskilling are no longer optional—they are primary for long-term economic security.
The ultimate retirement account hiding in plain sight.
— Dr. Evan Carter, Behavioral Economist, University of Chicago
| Educational Path | Avg. Cost | Median Lifetime Earnings |
|---|---|---|
| Vocational Certificate (e.g., HVAC Technician) | $16,000 | $2.2 Million |
| Associate’s Degree (e.g., Dental Hygienist) | $38,000 | $2.6 Million |
| Bachelor’s Degree (e.g., Software Engineer) | $127,000 | $3.5 Million |
Optimizing Financial Well-being: The Role of Benefits and Strategic Planning
Securing a higher-paying job through education is a significant achievement, but the paycheck itself is only one part of the total compensation picture. What many overlook are the financial benefits—from retirement plans to health savings accounts—that act as powerful wealth-building tools. Understanding and utilizing these benefits is not just about saving money; it’s about creating a foundation for long-term economic security.
Ignoring these provisions is like leaving a portion of your salary on the table. A surprising number of people do just that. According to the Employee Benefit Research Institute (EBRI), nearly 32% of private industry workers with access to a defined contribution plan, like a 401(k), do not participate. This represents a massive missed opportunity for compounding growth.
Leveraging Employer and Government Benefits for Financial Stability
The landscape of available benefits is vast, encompassing offerings from both employers and government entities. Employer-sponsored benefits often include health insurance, retirement savings plans with company matching, disability insurance, and life insurance. These programs provide a critical safety net, protecting individuals and families from catastrophic financial shocks that could otherwise derail their economic progress.
Beyond the workplace, various government programs and tax incentives are designed to bolster financial health. Tax credits for education, childcare, and energy-efficient home improvements directly reduce tax liability, freeing up cash for saving or investing. For many, navigating these options can feel overwhelming, which is why a clear understanding of the interplay between different financial tools is so primary. The key is to see these benefits not as isolated perks, but as interconnected components of a larger financial engine.
Strategic Financial Planning: Integrating Benefits for Long-Term Growth
A proactive approach to financial planning involves weaving these benefits into your overarching wealth management strategies. Simply enrolling is not enough. You must actively manage and optimize these accounts to align with your personal financial goals, whether that’s retiring early, funding a child’s education, or building generational wealth. This is where a personalized strategy becomes invaluable.
Think of it like cooking a meal. You have various ingredients in your pantry—your salary, your 401(k), an HSA, and maybe some tax credits. A great cook doesn’t just throw them in a pot; they combine them in the right proportions and sequence to create a delicious, cohesive dish. Your financial plan should do the same, ensuring each benefit works in concert with the others. But how many people actually review their benefit choices annually?
Retirement Planning and Benefit Maximization
For most people, the most significant employer benefit is the retirement plan, typically a 401(k) or 403(b). The absolute first step should always be to contribute enough to receive the full employer match. This is an immediate, guaranteed return on your investment—something you won’t find anywhere else in the financial markets.
For an employee earning $70,000 with an employer who matches 100% of contributions up to 4% of salary, failing to contribute that 4% means walking away from $2,800 in free money each year. Over a 30-year career, with modest market growth, that missed match could amount to hundreds of thousands of dollars in lost retirement funds. Exploring the common pitfalls in personal finance often reveals that neglecting the company match is one of the most frequent and costly errors.
Health and Wellness Benefits: Economic Implications
Health-related benefits extend far beyond just insurance premiums. High-deductible health plans (HDHPs) are often paired with a Health Savings Account (HSA), a uniquely powerful financial tool. Dr. Evan Carter, a behavioral economist at the University of Chicago, describes the HSA as “the ultimate retirement account hiding in plain sight.”
Contributions to an HSA are tax-deductible, the funds grow tax-free, and withdrawals for qualified medical expenses are also tax-free—a triple tax advantage. After a certain age, the funds can be withdrawn for any reason (though they become subject to income tax like a traditional IRA), making it a flexible supplement to retirement savings. Maximizing HSA contributions creates a dedicated fund for healthcare costs in retirement, protecting your primary investment portfolio from being depleted by medical bills.
Here is a simple checklist for getting started:
- Audit Your Current Benefits: Annually review every benefit available to you—from retirement matching to wellness stipends (and don’t forget commuter benefits!). Create a document listing what you are enrolled in and what you are eligible for.
- Define Your Goals: Align benefit contributions with specific short-term and long-term goals. Are you saving for a down payment or maximizing retirement? Adjust your strategy accordingly.
- Maximize Free Money: Prioritize capturing every dollar of employer matching in your 401(k) and any seed money offered for your HSA. This is the lowest-hanging fruit.
- Understand the Synergy: Learn how different accounts work together. See real-world examples by reviewing case studies of financial synergy to understand the powerful combinations available.
- Consult a Professional: If you feel overwhelmed, consider a fee-only financial advisor to help create a cohesive plan that integrates your unique benefit package with your overall financial life.
Ultimately, your benefits package is a dynamic component of your financial health that requires regular attention and strategic adjustments as your life and career evolve.
Navigating Market Opportunities: A Financial Perspective on Emerging Trends
Financial markets are much more than just numbers on a screen; they are a real-time reflection of human behavior, policy shifts, and breaking news. For the savvy investor, understanding the interplay between a government announcing new tax benefits and the subsequent stock market reaction is underlying. These events create ripples that can turn into profitable waves. Money follows information.
Think of the market like a grocery store manager constantly adjusting inventory. When news breaks about a new health trend or a supply chain disruption, the manager doesn’t wait; they immediately change their orders to meet anticipated demand. Similarly, financial markets react instantly to shifts in educational attainment, benefit policies, and economic news, repricing assets based on future growth prospects. What many overlook is how even seemingly small policy changes can signal a major market rotation. A recent report from the Brookings Institution found that federal investments in renewable energy tax credits were followed by a 34% increase in private funding for the sector within 18 months.
Identifying Growth Sectors Driven by Information and Skills
Pinpointing the next high-growth area often starts with looking at where society is investing its time and resources—specifically in education and workforce development. When a large portion of the population upskills in a particular area, like data science or sustainable engineering, it creates a talent pool that attracts corporate investment. This creates a feedback loop of growth. Companies move in, jobs are created, and the local economy benefits, which in turn boosts related stocks.
Dr. Elena Vance, a chief investment strategist at BlackRock, explains, “We’re seeing a direct correlation between national educational initiatives and sectoral performance. The recent push for digital literacy, for example, isn’t just a social good; it’s fueling a predictable expansion in EdTech and cybersecurity firms.” This is where investors can find an edge. But how do you separate the signal from the noise? The key is analyzing the data behind the headlines, a process explored in our data-driven analysis of these dynamics.
The synergy can be surprisingly direct. For instance, when a large corporation announces an expanded employee tuition reimbursement program (a corporate benefit), it’s not just an HR story. It’s an investment signal. The company is betting on the long-term value of a highly-skilled workforce, suggesting confidence in its future growth—a detail often missed by those who don’t look for these real-world examples of synergy. The most compelling opportunities often lie at the intersection of these seemingly separate fields, requiring a more holistic outlook.
Ultimately, the challenge isn’t just noticing that a trend exists. It’s about understanding its financial implications and positioning your portfolio before the broader market prices it in completely.
Future Economic Landscapes: Forecasting the Integrated Impact
Projecting the future of our economy requires looking beyond single data points. It’s about understanding how news, education, and financial benefits are becoming increasingly intertwined. The way information spreads, the skills we value, and the safety nets we build are no longer separate conversations; they are merging into a single, complex system. This integration presents both significant challenges and surprising opportunities for growth and stability.
Technological Disruption and its Economic Ripple Effects
Automation and artificial intelligence are fundamentally reshaping the job market. This isn’t just about robots on an assembly line. A recent report from the Brookings Institution suggests that for every job displaced by AI, approximately 1.74 new roles are created in related sectors like data analysis, AI ethics, and system maintenance. This creates a massive demand for continuous learning. The old model of getting a four-year degree that lasts a lifetime is like buying a single train ticket for a cross-country journey; today’s economy requires a transit pass for constant travel.
This reality forces a major re-evaluation of employee benefits and corporate finance. Companies must now invest heavily in reskilling and upskilling programs just to stay competitive. The financial implication is clear: budgets once allocated to traditional benefits are shifting toward educational stipends and on-demand training platforms. What most people miss is how this affects corporate balance sheets, turning education from a simple “perk” into a core operational expense. Navigating these evolving trends in news, education, and finance is now a critical leadership skill.
Global Economic Interdependencies: A Holistic View
No economy operates in a vacuum. The connections between nations through trade, information, and talent flow mean that a change in one area can have immediate effects thousands of miles away. Understanding these connections is primary for forecasting financial trends and developing sound policy. It demands a broader perspective than simply looking at domestic GDP or employment figures.
The Role of International News in Financial Markets
The speed at which global news travels directly impacts financial market volatility. A political announcement in Europe or a supply chain disruption in Asia can trigger billions of dollars in trades within minutes. For example, when a major semiconductor manufacturer announces production delays, tech stocks globally can dip based on the anticipated impact—long before any physical product shortages occur. This instantaneous reaction is fueled by algorithmic trading that parses news headlines for keywords.
But how accurately do these algorithms—and the human traders overseeing them—interpret the nuances of a situation? Misinformation or poorly translated reports can create artificial market swings, presenting risks and opportunities. This highlights the need for investors to develop a more holistic outlook and compare integrated strategies for information analysis rather than relying on single sources.
Cross-Border Education and Skill Transfer
The rise of remote work and online learning has made talent a global commodity. A software developer in Brazil can contribute to a project based in Germany, while a student in India can earn a certificate from a U.S. university without ever leaving home. This global talent pool allows companies to access specialized skills more easily, but it also creates intense competition for local workers.
This dynamic challenges traditional benefit structures and national education policies. Governments must now consider how to retain top talent while also preparing their workforce to compete on a global stage—a balancing act that many are still trying to figure out. The financial policies that support this, from tax incentives for remote workers to funding for international education partnerships, will become increasingly important in shaping which economies thrive.
Practical Steps for Economic Empowerment: A Synergistic Approach
Moving from broad economic theories to personal action requires a clear strategy. Treating news, education, benefits, and finance as separate silos is like trying to build a car with four different sets of instructions; the pieces will never quite fit together. The key is to create a personal system where each element informs the others, creating a cycle of growth. This requires adopting holistic financial growth strategies rather than tackling goals one by one.
Start by actively connecting financial news to your personal development. A report from the Financial Health Network suggests that 72% of financially healthy individuals regularly consume news related to their industry. When you read about emerging tech or shifting market demands, don’t just see it as information. Ask yourself, what skill could I learn to meet that demand? This transforms passive news consumption into an active career development plan, guiding your educational choices toward real-world opportunities.
This is your economic roadmap.
Next, audit your workplace benefits with a financial lens. What most people miss is that benefits are not just a safety net; they are an active financial tool. A high-deductible health plan with a Health Savings Account (HSA) isn’t just for medical bills; it’s a triple-tax-advantaged investment vehicle. Fully understanding and maximizing these tools can free up hundreds, if not thousands, of dollars annually for investment or debt reduction, a concept explored in our beginner’s guide to financial integration.
Finally, schedule a quarterly review to sync all these moving parts—think of it as a personal “state of the union” for your finances. This process of continuous alignment ensures your financial plan remains resilient and responsive, rather than a static document that gathers dust.
Beyond the Blueprint: Are You Prepared for the Next Economic Evolution?
The framework connecting news, education, benefits, and finance is not static; it’s accelerating. As artificial intelligence automates information analysis and remote work redefines the value of location-based benefits, the speed at which skills become obsolete will only increase. The strategies that built wealth over the last decade may not be sufficient for the next. The real challenge, then, isn’t just mastering the current system, but developing the agility to adapt to the one that’s coming. With information becoming both more accessible and more overwhelming, the ultimate question is no longer about having a plan, but about your capacity to rebuild it. How will you ensure your personal economic engine is designed not just to run, but to evolve?
Frequently Asked Questions
How does access to reliable news influence personal financial decisions?
Reliable news provides the required context for financial choices, from everyday spending to long-term investments. It informs you about inflation, interest rate changes, and policy shifts, allowing you to move from a reactive to a proactive financial stance and avoid being caught off guard by market volatility.
What is the long-term economic impact of investing in higher education?
Investing in higher education is a direct investment in human capital, which boosts earning potential and financial resilience. Data consistently shows a strong correlation between educational attainment and higher lifetime earnings. It equips individuals with in-demand skills, driving both personal wealth and broader economic productivity.
Can maximizing employment benefits significantly improve overall financial health?
Absolutely. Employment benefits like 401(k) matching, Health Savings Accounts (HSAs), and insurance are a critical part of total compensation. Maximizing them is like claiming your full salary, providing a safety net against financial shocks and creating powerful, often tax-advantaged, vehicles for long-term wealth accumulation.
How do global economic news and local benefit policies interact?
Global economic news, such as trade policy changes, can influence market performance and inflation, directly impacting your investment portfolio and cost of living. Local benefit policies, like state-sponsored training programs or tax credits, can provide tools to navigate these larger trends, creating opportunities to upskill or reduce your financial burden in response to macroeconomic shifts.
What are the key financial strategies for navigating an evolving information-driven economy?
Key strategies include continuous learning to prevent skill obsolescence and aligning your education with market demands. It’s also important to integrate all financial tools—salary, investments, and employment benefits—into a cohesive plan. Most importantly, one must develop the agility to adapt this plan as new information and economic trends emerge.